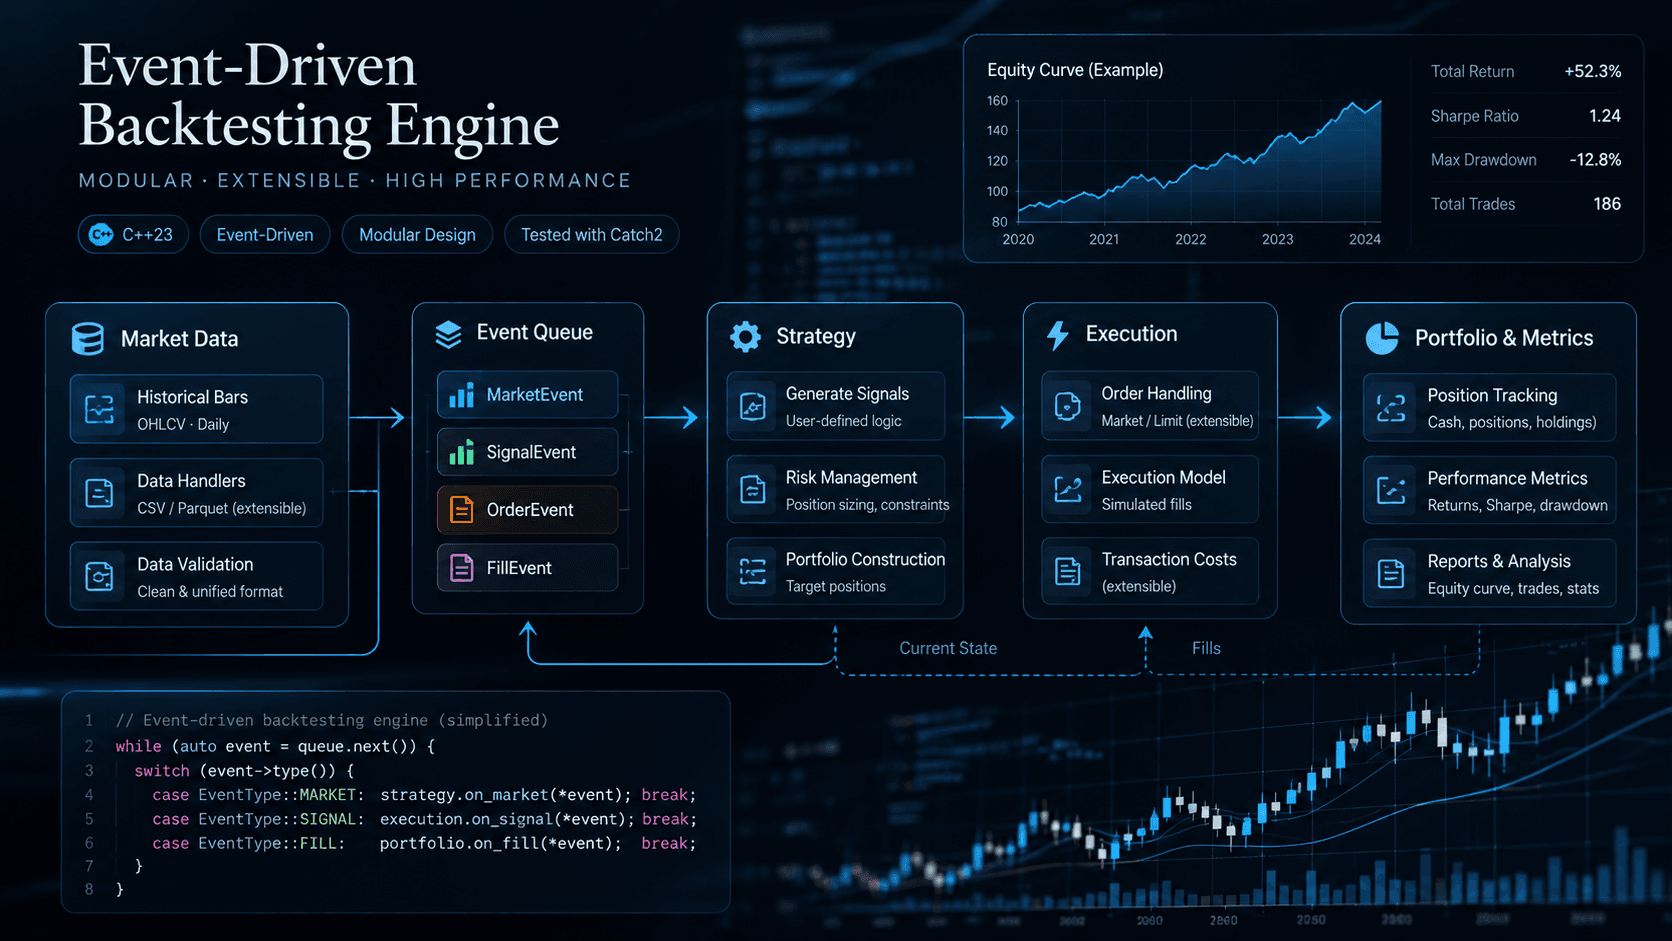
Event-Driven Backtesting Engine
An event-driven backtesting engine for systematic trading strategies using daily market data. The architecture separates market, signal, order, and fill events and is designed around deterministic historical-data processing, reproducible portfolio accounting, next-available-open execution, performance metrics, and end-to-end validation.
Python
Catch2
CTest